China: Huayi Group Q3 Report Breakdown: Propylene Chain Sees Volume and Price Gains, Coatings Sales Drop Nearly 20%
Key facts
- Huayi Group reported Q3 2026 revenue of 13.853 billion yuan, a 15.51% year-on-year increase, with net profit rising 1,372.69% to 156 million yuan
- The average propylene price in Shandong reached 8,753 yuan per ton in Q3 2026, marking a 35.64% year-on-year increase driven by geopolitical tensions
- Huayi Group's first three quarters 2026 revenue totaled 39.330 billion yuan, up 7.09% year-on-year, while net profit attributable to shareholders climbed 73.89% to 1.010 billion yuan
- The company's net profit excluding non-recurring items turned positive at 6.2428 million yuan in Q3 2026, reversing a loss of 38.7594 million yuan in the same period last year
- Guangxi Huayi Energy Chemical was consolidated into Huayi Group's financial statements on August 31, 2026, marking the first operational data disclosure since the acquisition
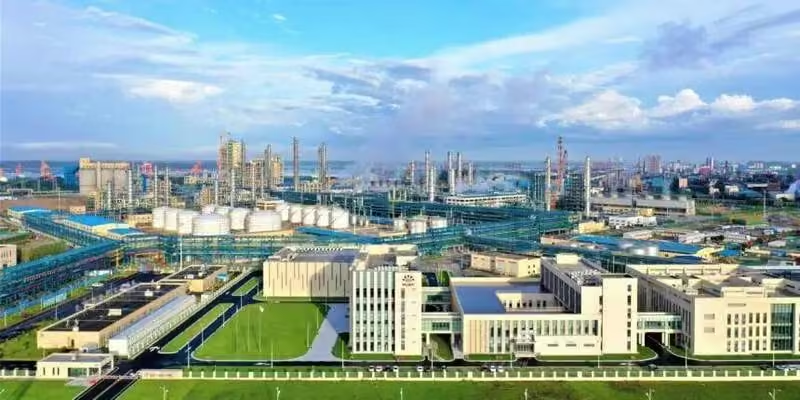
Hui Zheng Information reported on October 26 that Huayi Group released its third-quarter 2026 financial report. The company recorded revenue of 13.853 billion yuan for the quarter, a 15.51% year-on-year increase. Net profit attributable to shareholders rose 1,372.69% to 156 million yuan, while net profit excluding non-recurring items turned positive at 6.2428 million yuan, compared with a loss of 38.7594 million yuan in the same period last year. For the first three quarters, revenue reached 39.330 billion yuan, up 7.09% year-on-year. Net profit attributable to shareholders climbed 73.89% to 1.010 billion yuan, and net profit excluding non-recurring items increased 60.60% to 584 million yuan. This marks the first operational data disclosure since Guangxi Huayi Energy Chemical was acquired and consolidated into the group’s financial statements on August 31, 2026.
A detailed business analysis released by Huayi Group indicates significant divergence in production, sales volume, and average pricing across its six main product lines: methanol and acetic acid derivatives, industrial gases, propylene and downstream products, coatings and resins, tires, and fluorine-containing materials.
For the first three quarters, the production of methanol, acetic acid, and downstream products totaled 4.6069 million tons, with sales volume at 3.5754 million tons. The average price stood at 2,641.82 yuan per ton, generating sales revenue of 9.446 billion yuan. These figures represented year-on-year increases of 160.6%, 183.3%, 12.0%, and 217.4%, respectively. The surge in production, sales, and revenue was primarily driven by the expanded reporting scope following the consolidation of Guangxi Huayi Energy Chemical. According to data from the Mai Huasu Research Institute, the core driver behind the rise in acetic acid prices in the third quarter of 2026 was supply contraction. INEOS idled approximately 500,000 tons per year of acetic acid capacity at its Hull facility in the United Kingdom. Meanwhile, domestic acetic acid operating rates dropped to 79.32% at one point, with major plants in Tianjin and Shanghai halting operations. Coupled with reduced methanol imports and low inventory levels, acetic acid gross profit recovered to 1,385 yuan per ton by the end of September, with a gross margin of 30.26%.
Industrial gas production and sales volume both stood at 626,600 thousand cubic meters for the first three quarters, down 21.9% year-on-year. The average price increased 17.5% to 1,213.34 yuan per thousand cubic meters, while sales revenue fell 8.2% to 760 million yuan. Data from the Mai Huasu Research Institute shows that the average price of liquid argon surged 55.15% quarter-on-quarter in the third quarter, driven by lower operating loads of air separation units and demand from the photovoltaic and electronics sectors. However, prices for liquid oxygen and liquid nitrogen remained under pressure due to weak demand and ample supply.
Propylene and downstream products were the only category among the six to see simultaneous increases in production, sales volume, and average price. Production reached 3.1084 million tons in the first three quarters, up 11.7% year-on-year. Sales volume rose 4.7% to 1.3510 million tons, while the average price increased 8.7% to 7,290.96 yuan per ton. Sales revenue grew 13.8% to 9.850 billion yuan. Notably, the growth rate in production significantly outpaced that of sales. According to the Mai Huasu Research Institute, the average propylene price in Shandong reached 8,753 yuan per ton in the third quarter of 2026, a 35.64% year-on-year increase. The primary driver was the escalation of geopolitical tensions in the Middle East, which pushed up the prices of raw materials such as crude oil, propane, and methanol, thereby strengthening cost support for propylene. On the supply side, new domestic propylene capacity released in the third quarter was limited, and some facilities reduced operating rates due to cost pressures, resulting in no significant supply-side pressure. However, limited demand absorption led to a price correction. After peaking at 10,050 yuan per ton in early September, propylene prices retreated from their highs as PDH plants resumed operations and downstream margins compressed, dampening procurement enthusiasm.
Paints and resins recorded the steepest volume decline among the six product categories. Output for the first three quarters reached 24,500 metric tons, down 12.9% year-on-year, while sales volume fell 19.3% to 24,000 metric tons. The average selling price rose 15.7% to 29,080.43 yuan per metric ton, yet total revenue contracted 6.7% to 697 million yuan. The drop in sales volume significantly outpaced the decline in production, and the price increase ranked among the highest across all six categories.
The 2026 paints sector is being weighed down by the continued contraction in real estate completions, which has squeezed demand for architectural and decorative coatings. The China Coatings Industry Association projects that annual paint output will decline by approximately 3%, signaling a shift toward competition within an existing market base. Upstream raw materials, such as epoxy resins, remain constrained by weak end-user demand, with liquid E-51 resin producers operating at a loss per metric ton and maintaining low utilization rates for an extended period. Huayi’s 19.3% contraction in paint and resin sales far exceeds the industry-wide output decline of roughly 3%.
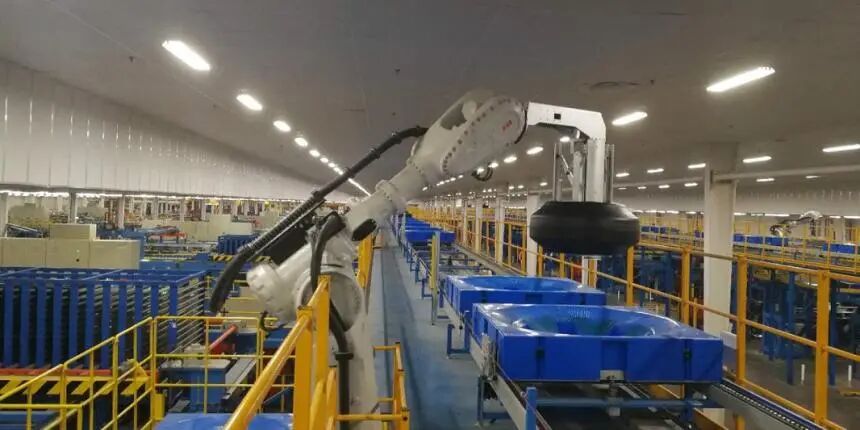
Tire production in the first three quarters reached 13.0828 million units, a 2.8% year-on-year decline, while sales volume stood at 13.3574 million units, down 2.1% from the same period last year. The average selling price per unit fell 1.2% to 636.94 yuan, resulting in revenue of 8.508 billion yuan, a 3.3% decrease. Sales volume slightly exceeded production figures.
For fluorine-containing materials, production in the first three quarters was 237,700 tons, up 1.4% year-on-year, and sales volume rose 7.1% to 92,600 tons. The average price per ton decreased 1.2% to 35,659.66 yuan, yet total revenue increased 5.8% to 3.303 billion yuan. The growth rate in sales volume outpaced that of production, and the decline in average price marked the only year-on-year price drop among the six product categories reported.
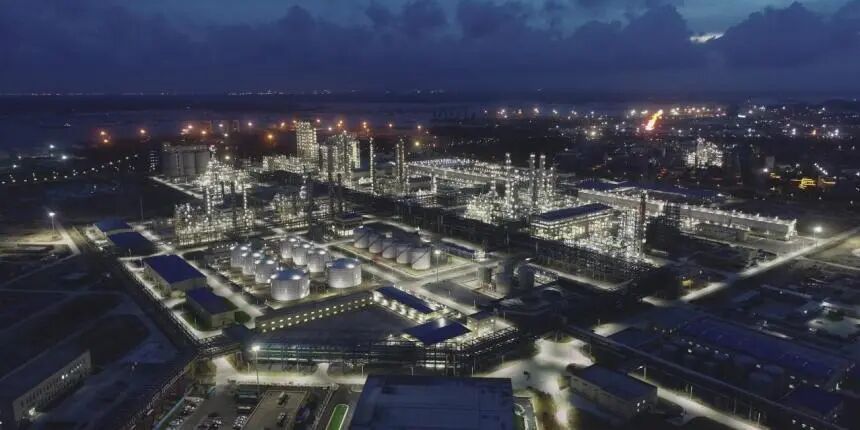
At the project level, the polyether unit of the Qinzhou Phase III HPPO facility achieved a successful first startup in May, while the methanol-to-olefins unit completed its process integration in June. Concurrently, the 300,000-ton-per-year vinyl acetate unit began producing qualified products during the same period. The 100,000-ton-per-year green methanol project commenced operations in December 2025. In the fluorine materials sector, Sanai Fu has fully resumed production and operations following the suspension and remediation measures at its Inner Mongolia Wanhao site. Meanwhile, Fujian Fuyou has seen continued improvement in its fine chemical products, with fourth-generation refrigerants and PVDF currently representing its largest production volumes. These developments hold medium- to long-term significance for Huayi Group’s strategic expansion from basic chemicals into high-end polyolefins and fine materials.
Chnchemicals take
The significant surge in propylene prices, driven by geopolitical tensions and rising raw material costs, signals a challenging environment for downstream chemical producers who face increased input expenses. This cost pressure may compress margins for buyers and traders unless they can effectively pass these increases to end consumers. Investors should monitor how such volatility impacts the profitability of companies reliant on propylene as a key feedstock, as sustained high prices could erode operational efficiency across the supply chain.
Frequently asked questions
What was the year-on-year change in Huayi Group's net profit attributable to shareholders in Q3 2026?
Huayi Group's net profit attributable to shareholders rose 1,372.69% to 156 million yuan in Q3 2026. This significant increase coincided with the consolidation of Guangxi Huayi Energy Chemical into the group's financial statements.
How did the average propylene price in Shandong change in Q3 2026 compared to the same period last year?
The average propylene price in Shandong reached 8,753 yuan per ton in Q3 2026, a 35.64% year-on-year increase. This rise was driven by geopolitical tensions in the Middle East pushing up raw material costs.
What factors contributed to the cost support for propylene prices in the third quarter of 2026?
Geopolitical tensions in the Middle East escalated, pushing up prices for crude oil, propane, and methanol. These increased raw material costs provided stronger cost support for propylene production and pricing.